How state-mandated retirement plans work
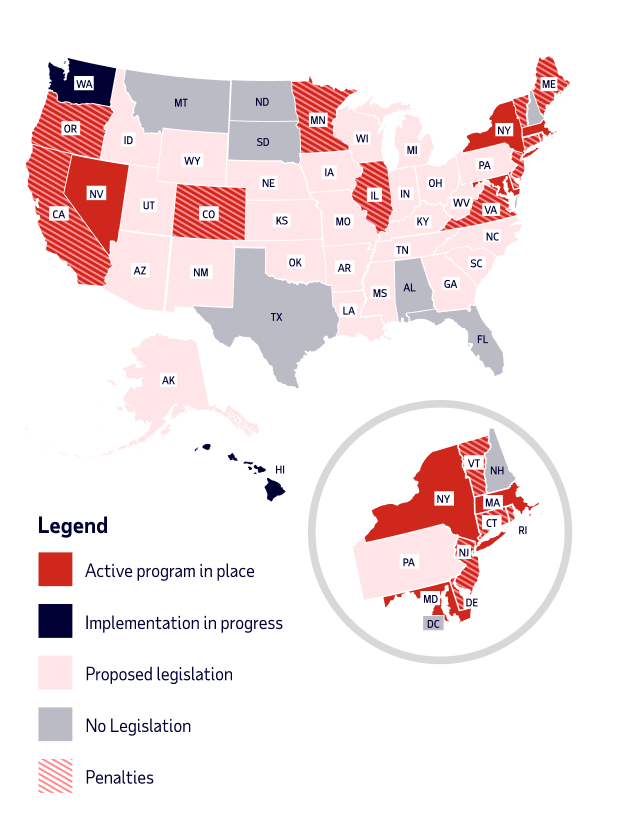
More than 25 states have proposed state-mandated retirement plan legislation, and 15 states have active state-sponsored retirement plans. Find out how these new laws impact your business.
Retirement plans
Know your state's mandate
Select a location to see your state’s retirement legislation. As state-mandated retirement legislation continues to evolve across the country, employers should check with their local representatives for the latest updates.
If you do not see your state listed, it currently has no active program or has not passed retirement mandate legislation. Check back regularly to see if your state has been added.
Retirement Services
More flexibility. More choices. With ADP, you get so much more.
What is a state retirement plan?
As states continue to pass retirement legislation, employers across the county must now choose a retirement plan that is right for their business and their employees – a critical aspect of retaining top talent. Here’s what employers need to know about mandatory, state sponsored retirement plans:
When states require employers to provide their employees with retirement savings opportunities, it’s known as a state-mandated retirement or state-sponsored retirement plans. Businesses generally have two ways to comply with these laws – enroll their employees into a state-sponsored retirement plans or sponsor a plan through the private market, such as those offered by ADP.
The inner workings of mandatory state retirement plans depend on the state, but some commonalities exist. Typically, plans are administered through payroll deductions, and employees are automatically enrolled but can opt out or change how much they contribute. Employers themselves are usually prohibited from contributing to the plans.
There are, however, some exceptions to these general guidelines. For instance, Massachusetts permits Safe Harbor matching contributions by employers. Business owners should check with local authorities for specific information on how their state-sponsored retirement plan works.
State-sponsored retirement plans are commonly Roth individual retirement accounts (IRA). With this type of savings, employee contributions are deducted from post-tax income, which means their money is generally tax-free at the time of withdrawal. A traditional IRA is funded with pretax payroll deductions, lowering the employee’s taxable income. However, when the individual draws from the account, the money is subject to taxes.
State-mandated or state sponsored retirement plans are designed for low to moderate-income wage earners who work for small and midsized businesses in the public sector. These plans are entirely separate from the state-funded retirement programs for public employees.
The requirements for state-mandated retirement benefits largely depend on individual jurisdictions, the size of the organization, and how long it has been in business. Generally, employers must enroll their employees in state-sponsored retirement plans if they don’t offer another retirement plan and perform the detailed administrative and reporting work necessary under state law. These tasks can be daunting, so many employers choose one of ADP’s easy-to-manage plans instead.
Employee requirements also may vary. In states that sponsor Roth IRAs, participants must not earn more than the IRS maximum to be eligible for such plans.
Is a 401k Mandatory for Employers
Employers do not have to offer a 401(k) plan. However, in some states a retirement plan is required by state law. The Employee Retirement Income Security Act (ERISA) is the federal law that sets minimum standards for retirement plans in the private industry. It only requires that those who establish plans must meet certain minimum standards.
State-sponsored retirement plans have pros and cons, which business owners must carefully weigh. On the one hand, government-run programs are generally a low-cost solution with few fiduciary responsibilities for employers. On the other hand, these plans tend to have inflexible, one-size-fits-all designs, and businesses that miss registration deadlines may be penalized. Ultimately, whether employers choose to participate in state-sponsored retirememt plans or offer their own through the private market, the important thing to remember is that retirement benefits are a valued commodity among employees and can help improve recruitment and retention.
Why mandate retirement plans?
Some states have begun mandating state retirement plans to address this country's retirement savings gap. Their response is based on research that shows:
 The average working household has virtually no retirement savings.1
 Employees are more likely to save when they have access to a 401(k) or similar plan by their employer.2
 Only four in 10 businesses with less than 100 employees offer retirement benefits.3
Sign up for a 401(k) plan today and avoid penalties
Up to 3 years of retirement plan administrative costs may be covered with SECURE 2.0 Act tax incentives. Talk to an ADP Retirement Specialist.
 Frequently asked questions about mandates for state retirement plans
As state-sponsored retirement plans become more common, several states have already passed legislation, including:
- California
- Colorado
- Connecticut
- Delaware
- Hawaii
- Illinois
- Maine
- Maryland
- Massachusetts
- Minnesota
- Nevada
- New Jersey
- New Mexico
- New York
- New York City
- Oregon
- Rhode Island
- Vermont
- Virginia
- Washington
State-sponsored retirement plans legislation is still in flux in many states. As laws change, it is important to check with your local representative for the latest updates.
- Alaska
- Arizona
- Arkansas
- Georgia
- Idaho
- Indiana
- Iowa
- Kansas
- Kentucky
- Louisiana
- Michigan
- Mississippi
- Missouri
- Nebraska
- New Hampshire
- North Carolina
- North Dakota
- Ohio
- Oklahoma
- Pennsylvania
- South Carolina
- Tennessee
- Utah
- West Virginia
- Wisconsin
- Wyoming
While state-sponsored retirement plans are rising in popularity, most states have not considered mandating a plan – yet. It is important to check with your local representatives for the latest updates.
- Alabama
- Florida
- Montana
- South Dakota
- Texas
Employers generally are not required to offer their employees retirement benefits. However, some states have state-sponsored retirement plans with mandatory participation. In these jurisdictions, eligible employers must enroll their employees in the state program or provide retirement benefits on their own.
Secure Choice is the name of state-sponsored retirement plans in Illinois and New York. Although they have similar naming conventions, these plans are not the same. Each has its own requirements and participation rules.
Employers in jurisdictions with mandatory state retirement plans who don't comply with the requirements or miss enrollment deadlines may be penalized. The exact monetary amount of the penalty varies by state.
Mandatory contributions are contributions employers or employees are required by law to make and cannot opt-out of. Some states make it mandatory for state employees or others to pay into a retirement plan.
Let's Talk
Speak to a retirement specialist to understand your state's legislation and know your options.
By submitting this form, you acknowledge that you have read our Privacy Statement for Business Contacts and agree to our Terms of Use.
This information is intended to be used as a starting point in analyzing state-mandated retirement plans and is not a comprehensive resource of all requirements. It offers practical information concerning the subject matter and is provided with the understanding that ADP is not rendering legal or tax advice or other professional services.
Unless otherwise agreed in writing with a client, ADP, Inc. and its affiliates (ADP) do not endorse or recommend specific investment companies or products, financial advisors or service providers; engage or compensate any financial advisor or firm for the provision of advice; offer financial, investment, tax or legal advice or management services; or serve in a fiduciary capacity with respect to retirement plans. All ADP companies identified are affiliated companies.
ADP, Inc. is affiliated with ADP Broker-Dealer, Inc. (“ADP BD”), a limited purpose broker dealer registered with the Financial Industry Regulatory Authority (“FINRA”), and operating pursuant to Securities and Exchange Commission (“SEC”) Rule 15c3-3(k)(2)(i), approved by FINRA to offer 401(k) and SEP/ SIMPLE IRAs, and related retirement plans (the “Retirement Products”) on a payroll deduction basis.
ADPRS-20230927-4974